The Financial Conduct Authority (FCA) published proposals on 7 October 2025 for an industry-wide motor finance compensation scheme covering customers treated unfairly between 2007 and 2024. In its announcement, the FCA said it expects around 14 million agreements to be unfair under its proposals, with average compensation of about £700 per agreement and lenders potentially paying out £8.2 billion.
Corporate INTL Newsroom · Banking & Finance
FCA Proposes Motor Finance Compensation Scheme Worth an Estimated £8.2 Billion
By The Corporate INTL Newsroom · 8 October 2025
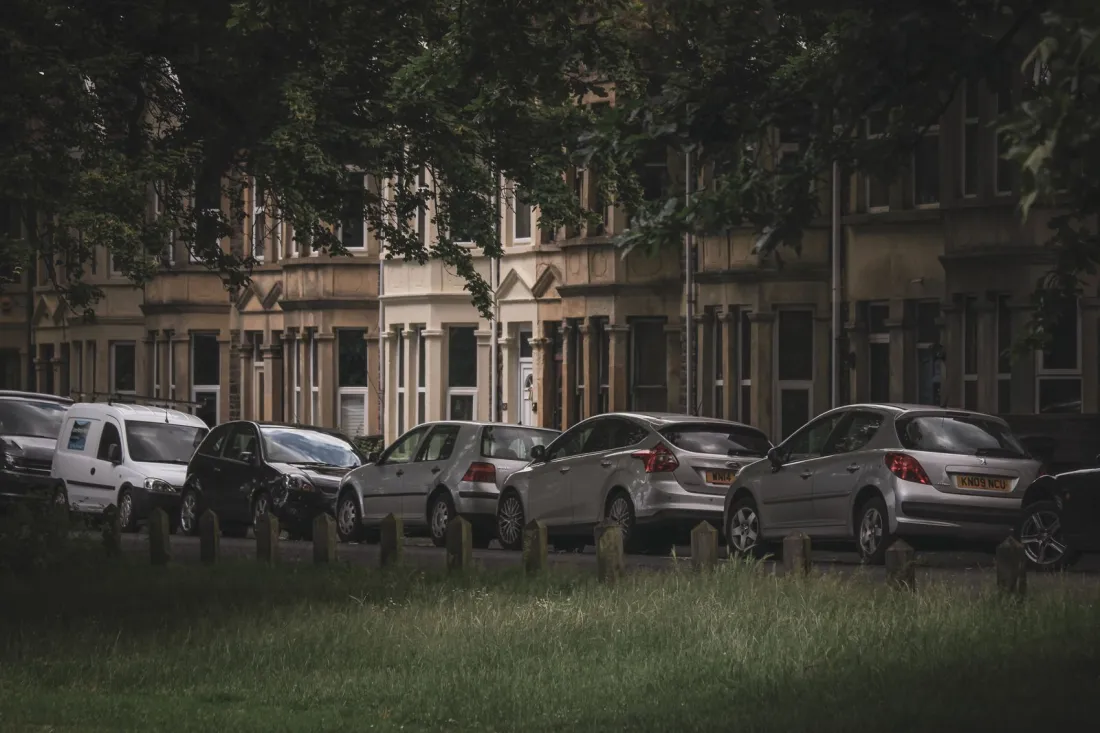
The proposals are set out in consultation paper CP25/27 and follow the UK Supreme Court's judgment of 1 August 2025 in the motor finance commission appeals.
What the scheme would cover
The scheme would apply to regulated motor finance agreements taken out between 6 April 2007 and 1 November 2024 where commission was payable by the lender to the broker. The consultation identifies three types of arrangement that may give rise to an unfair relationship: discretionary commission arrangements, high commission arrangements and tied arrangements.
How it would work
Lenders would pay compensation, with the FCA monitoring firms and the Financial Ombudsman Service assessing disputes where customers disagree with a firm's decision. Once the scheme goes live, lenders would contact customers who have already complained, and their cases would be reviewed if they do not respond within one month. Customers who have not complained would be contacted within six months of the scheme starting and have six months to opt in. Borrowers who cannot be traced would have one year from the start of the scheme to claim directly from their lender.
Customers who complained before the scheme starts could opt out, in which case their complaint would go to the Ombudsman. The FCA encouraged consumers to complain to their lender now using its template letter, noting they do not need a claims management company or law firm, which could take a significant share of any compensation.
What happens next
The FCA said compensation could start to be paid in 2026, once final rules are made. Lenders and brokers should model their exposure under the proposed criteria and prepare customer contact, data and complaint handling processes before the motor finance compensation scheme goes live.
Sources
Looking for legal or business advice?
Tell us what you need and the Corporate INTL team will help you find the right lawyer or adviser from our members in 150+ jurisdictions.
1What you need2Your details
More from the newsroom
All latest news → Related stories
Banking & Finance
Will UniCredit Buy Commerzbank? Why Control Is Expected This Month and What Changes
Banking & Finance
Binance Hack: Inside the $6.3bn Crypto Theft and What It Means for Customers
Banking & Finance