On 9 December 2025 the European Parliament and the Council reached a provisional political agreement on the Omnibus I simplification package. The European Commission welcomed the deal, which amends the Corporate Sustainability Reporting Directive (CSRD) and the Corporate Sustainability Due Diligence Directive (CSDDD), removing many companies from their scope and introducing more flexibility for those that remain.
Corporate INTL Newsroom · Corporate, Commercial & M&A
EU Reaches Political Agreement on Omnibus I to Simplify CSRD and CSDDD
By The Corporate INTL Newsroom · 10 December 2025
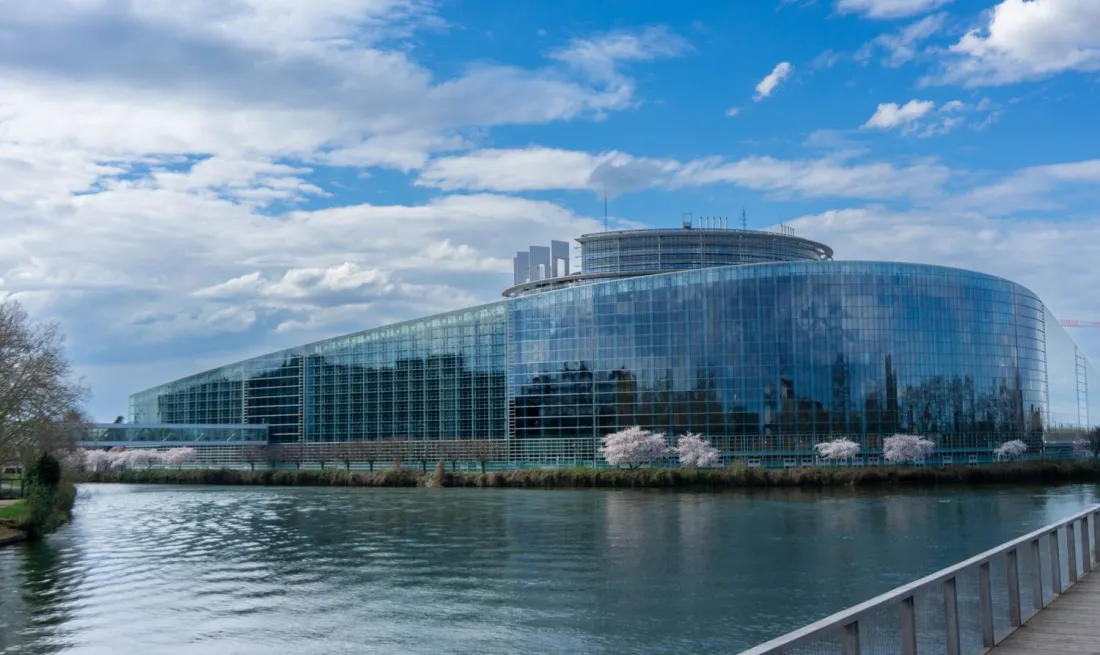
Sustainability reporting
According to the European Parliament, CSRD reporting will apply to EU companies with on average more than 1,000 employees and net annual turnover above €450 million. For non-EU companies the threshold is €450 million of turnover generated in the EU. Sector-specific reporting becomes voluntary, and companies with fewer than 1,000 employees may refuse requests for information that go beyond the voluntary standards. The Commission will set up a digital portal with templates and guidance on EU and national reporting requirements.
Due diligence
The CSDDD will apply only to EU companies with more than 5,000 employees and net annual turnover above €1.5 billion, and to non-EU companies with EU turnover above €1.5 billion. Companies in scope will take a risk-based approach across their chain of activities and should avoid requesting unnecessary information from businesses outside scope. They will no longer have to adopt a transition plan aligning their business model with the Paris Agreement. Liability for non-compliance is set at national rather than EU level, with fines of up to 3% of net worldwide turnover.
Background and next steps
The Commission proposed Omnibus I on 26 February 2025. In April 2025 the co-legislators adopted a separate stop-the-clock measure postponing CSRD reporting for companies that had not yet started and delaying the first phase of the CSDDD. The provisional agreement must now be formally approved by the Parliament and the Council. The amendments will take effect on the day of their publication in the Official Journal of the European Union.
Companies that prepared for reporting under the original thresholds should reassess whether they remain in scope, and groups with EU subsidiaries should review how the new turnover tests apply to them.
Sources
Looking for legal or business advice?
Tell us what you need and the Corporate INTL team will help you find the right lawyer or adviser from our members in 150+ jurisdictions.
1What you need2Your details
More from the newsroom
All latest news → Related stories
Corporate, Commercial & M&A
How to Open a Business in Dubai: 9 Steps From Trade Licence to Corporate Tax Registration
Corporate, Commercial & M&A
Did the Warner Bros. Paramount Merger Go Through? How the $110bn Skydance Deal Cleared Regulators
Corporate, Commercial & M&A